
5 Signs Your Friend or Family Member Is Ready to Buy a Home
Not sure if someone in your life is actually ready to start the homebuying process? Here are five clear signals that now might be the right time to make an introduction to a mortgage professional.
And you wonder: are they actually ready? Or are they just talking?
The truth is, "ready to buy" looks different for everyone. But after nearly 30 years of helping Chicago-area families navigate the mortgage process, I have noticed some consistent patterns. Certain signals tend to show up before someone is genuinely close to making a move.
If someone in your life is showing these signs, it might be time to make an introduction.
Sign 1: They have been renting for a while and are starting to feel stuck
There is a moment that happens for a lot of renters — usually somewhere between year three and year five — where the math starts to feel wrong.
They have been paying rent for years, their landlord just raised it again, and they are starting to realize they have nothing to show for it. No equity. No stability. No ability to paint the walls without asking permission.
This is one of the most common triggers for someone to start seriously thinking about buying. If your friend is in this phase — frustrated with renting, curious about ownership, but not sure where to start — that is a perfect time to connect them with a mortgage professional.
A pre-approval conversation does not commit them to anything. It just gives them a realistic picture of what they can afford, which is usually the first thing they need to move from "thinking about it" to "actually doing it."
Sign 2: Their income has stabilized or grown recently
Mortgage lenders look at income consistency. Two years of steady employment history is the standard benchmark for most loan programs — and for good reason. It gives lenders confidence that a borrower can sustain their payments over time.
If someone in your life recently got a promotion, landed a more stable job after years of contract work, or finally hit a consistent income level after building a business, they may be in a much stronger position to qualify than they realize.
This is especially true for self-employed borrowers. Many assume that because their income is irregular or comes from multiple sources, they cannot qualify for a mortgage. That is often not the case. With the right documentation and the right loan program, self-employed buyers can absolutely get approved — they just need a lender who knows how to structure the file.
If your friend has been building toward financial stability and is starting to feel like they are finally there, that is a strong signal that a mortgage conversation is worth having.
Sign 3: They are actively saving — or already have a down payment
One of the clearest signs that someone is serious about buying is that they are putting money aside specifically for a home.
It does not have to be a 20% down payment. Many loan programs — including FHA loans, VA loans for veterans, and certain conventional programs — allow buyers to put down significantly less. Some first-time buyer programs in Illinois offer down payment assistance that can reduce the upfront cost even further.
But the act of saving intentionally is meaningful. It signals that someone has moved past the daydream phase and is actually preparing to make a move.
If your friend mentions they have been building up savings, ask them what they are saving for. If the answer involves a home, that is your cue.
Sign 4: They are talking about life changes that require more space
Life transitions are one of the biggest drivers of home purchases. And they tend to come with a sense of urgency that makes people more motivated to act.
Some of the most common ones I see:
- A growing family. A new baby on the way — or a second or third — has a way of making a two-bedroom apartment feel very small very quickly.
- A marriage or long-term partnership. Two people combining households often want a space that feels like theirs, not a compromise between two existing leases.
- A parent or family member moving in. Multi-generational living is increasingly common, and it often requires more space than a rental can provide.
- A remote work situation that is not going away. The need for a dedicated home office has pushed a lot of people to reconsider their living situation.
If someone in your life is going through one of these transitions and talking about needing more space, they are probably closer to buying than they think. The question is whether they have connected with someone who can help them figure out what is actually possible.
Sign 5: They keep asking you questions about your experience
This one is subtle, but it is one of the most reliable signals I have seen.
When someone is genuinely considering buying, they start asking questions. They want to know what the process was like for you. They ask how you found your lender. They want to know if it was as complicated as it sounds. They ask what you wish you had known.
These are not casual questions. They are research. The person asking them is trying to figure out if homeownership is realistic for them — and they are starting with someone they trust.
If a friend or family member has been asking you about your homebuying experience, that is a strong signal that they are in the early stages of seriously considering it. And the most helpful thing you can do is connect them with someone who can give them a straight answer about what their options actually look like.
What to say when you make the introduction
You do not need to oversell it. A simple message goes a long way:
"Hey, I worked with a mortgage guy in Chicago who was really helpful when I was buying. His name is David Braun — he's been doing this for almost 30 years and he's really straightforward. I can connect you if you want to just have a conversation."
That is it. No pressure, no commitment. Just an introduction to someone who can help them figure out where they stand.
And right now, if your referral leads to a conversation with me, I will send you a gift card as a thank-you. Because referrals are how my practice grows — and I want to make sure the people who trust me enough to share that trust are recognized for it.
Make an introduction and earn your gift card
If you have questions about the referral program or want to talk through a specific situation before making an introduction, feel free to reach out directly at david@davidbraunmlo.com.
David Braun | MortgageOS | NMLS #303007
Article Disclosure
This article is for educational and informational purposes only and does not constitute financial, legal, or tax advice. Mortgage rates, loan programs, terms, and eligibility requirements are subject to change without notice and may vary based on individual circumstances. Not all applicants will qualify. This is not a commitment to lend or a rate lock. Contact a licensed mortgage professional to discuss your specific situation.
David Braun | NMLS #303007 | Regional Mortgage Corporation NMLS #112327 | IL MB.031.0001577 | Licensed in Illinois, Indiana & Florida | Equal Housing Opportunity Lender. Verify on NMLS Consumer Access
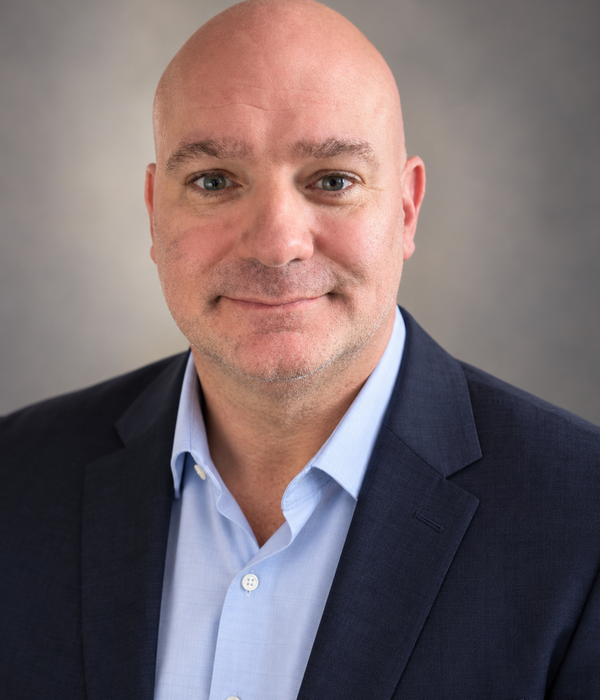
David Braun
Chicago Mortgage Loan Officer | MortgageOS | NMLS #303007
Nearly 30 years helping Chicagoland families navigate the mortgage process — from first-time buyers to self-employed borrowers.